02 Oct 2026
For a small business, year-end is a useful checkpoint for reviewing income, expenses, deductions, equipment plans, retirement contributions, estimated taxes, and records before the tax year closes. Some decisions depend on actions taken before the year closes.
Small business tax planning is not about spending money just to create a deduction. It is about understanding the numbers, identifying legitimate opportunities, considering timing where allowed, and keeping records that support the return.
What Is Small Business Tax Planning?
Small business tax planning involves reviewing income, expenses, deductions, credits, purchases, estimated payments, and other tax factors before year-end so a business can make informed decisions within applicable tax rules. The approach depends on business structure, accounting method, income, and circumstances.
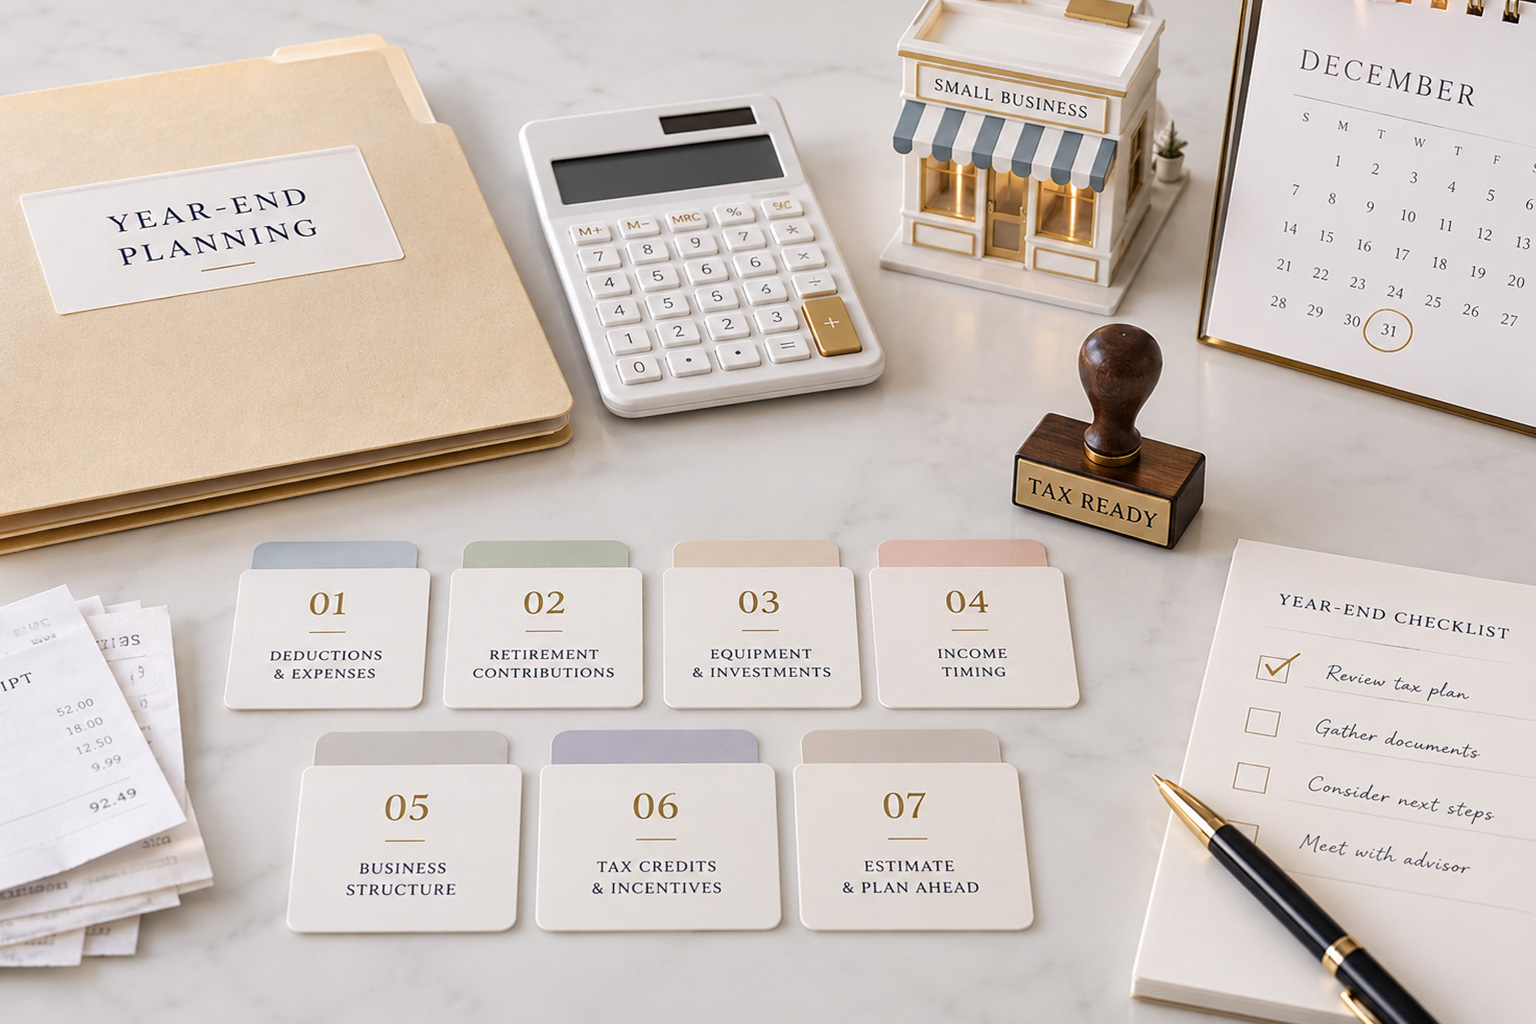
7 Year-End Tax Planning Moves for Small Businesses
1. Review Your Year-to-Date Income and Expenses
Start with a clear picture of where the business stands. Review revenue, operating expenses, payroll, contractor payments, outstanding invoices, and major purchases.
A current profit-and-loss statement can reveal missing transactions or unexpected results. The goal is to understand the financial position early enough to discuss legitimate planning options.
2. Review Potential Business Deductions
Review expenses that may qualify as ordinary and necessary business expenses. Examples may include business supplies, qualifying software, professional services, insurance, and other operating costs. Whether an expense is deductible, when it can be deducted, or whether it must be capitalized depends on the facts and applicable tax rules.
Keep business and personal spending separate, with documentation showing the purchase, business purpose, amount, and timing.
Remember that a deduction generally reduces taxable income; it does not reduce the tax bill dollar-for-dollar. Do not buy something unnecessary simply because it might produce a deduction.
3. Consider Timing of Income and Expenses
Timing can matter, but there is no single year-end rule for every business.
Cash-basis taxpayers generally recognize income when received and deduct expenses when paid, subject to special rules. Accrual-basis taxpayers generally recognize income when the right to receive it is established and expenses under rules concerning liability and economic performance.
A year-end payment or invoice may therefore have different tax results. Before changing transaction timing, confirm that the action is permitted under the business's accounting method and tax rules.
4. Review Equipment and Business Purchases
If the business already plans to purchase equipment, computers, certain technology, vehicles, or other qualifying property, year-end is a useful time to review the tax treatment.
Depreciation generally spreads the cost of qualifying business property over its recovery period. Section 179 may allow eligible taxpayers to elect to deduct the cost of qualifying property, subject to limits, business-income rules, and other requirements.
For tax years beginning in 2026, the maximum Section 179 expense deduction is $2,560,000, with a phaseout beginning when the cost of Section 179 property placed in service exceeds $4,090,000. The maximum Section 179 deduction for qualifying sport utility vehicles placed in service in 2026 is $32,000.
Current IRS guidance provides 100% special depreciation for certain qualified property acquired and placed in service after January 19, 2025, subject to eligibility rules.
These provisions are planning tools, not reasons to make unnecessary purchases.
5. Review Retirement Contributions
Business owners should review retirement plan options before year-end. Depending on the business and plan, options can include a SEP IRA, SIMPLE IRA, 401(k), or another qualified plan.
Contribution limits, eligibility, plan establishment dates, and funding deadlines vary. Some contributions can be made after year-end, while employee elective deferrals generally follow different timing rules.
For 2026, the IRS lists a $24,500 elective deferral limit for most 401(k) plans, a $17,000 general SIMPLE plan salary-reduction limit, and a $72,000 SEP maximum subject to the plan's percentage-of-compensation rules. Confirm the applicable limit and deadline before contributing or establishing a plan.
6. Check Estimated Tax Payments and Payroll Tax Responsibilities
Compare expected tax liability with payments already made. Sole proprietors, partners, and S corporation shareholders generally may need estimated tax payments when they expect to owe at least $1,000 when filing. Corporations generally have estimated-tax obligations when they expect to owe at least $500.
Underpayment penalties can apply, although safe-harbor and special rules can affect the result.
Estimated income tax is different from payroll tax. Payroll responsibilities can include employee withholding, Social Security and Medicare taxes, employer payroll taxes, and required filings. These obligations should be reviewed separately.
If income, payroll, or withholding changed significantly, review whether adjustments or additional payments are needed.
7. Organize Records and Prepare for Tax Filing
Good records help track income, identify deductions, prepare returns, and support reported items.
Before year-end, review income records, receipts, invoices, bank and credit-card statements, payroll and contractor records, asset purchases, applicable vehicle or mileage records, charitable contribution documentation, and prior-year tax documents.
Reconcile accounts and investigate missing documentation. For equipment, keep invoices, payment evidence, and placed-in-service information.
|
Year-End Move |
Why Review It |
What to Check |
|
Income and expenses |
Understand current tax position |
Revenue, expenses, outstanding items |
|
Business deductions |
Identify potentially deductible costs |
Receipts and eligibility |
|
Equipment purchases |
Review depreciation opportunities |
Purchase date and applicable rules |
|
Retirement contributions |
Review available contribution options |
Plan type and deadlines |
|
Estimated taxes |
Check whether payments are on track |
Income and payments made |
|
Records |
Prepare for tax filing |
Receipts, statements, payroll and contractor records |
What Expenses Can a Small Business Prepay
for Tax Purposes?
Prepaying an expense does not automatically make the entire amount deductible in the current tax year. Under the cash method, businesses generally deduct expenses when paid, but prepaid expenses may have to be allocated to the periods they cover. For example, a one-year insurance policy spanning two tax years may require the deduction to be divided between those years.
Accrual-basis businesses follow different rules, including requirements related to when liability is fixed and when economic performance occurs.
Before prepaying rent, insurance, subscriptions, or services for tax reasons, check the timing rules. The business should have a genuine operational reason for the expense rather than spending money solely to create a deduction.
How Can a Small Business Reduce Taxes Before Year-End?
A business can review potentially deductible expenses, planned equipment purchases, retirement contributions, available credits, income and expense timing, and estimated tax payments. Business structure can also affect tax treatment.
The right approach depends on entity type, accounting method, income, payroll, and business activity. Planning should focus on genuine business decisions, not artificial transactions.
When Should Small Businesses Start Year-End Tax Planning?
Start before the tax year closes rather than waiting for tax-return preparation. Some decisions, including placing qualifying property in service or making certain payroll and retirement-plan decisions, depend on actions taken during the year.
Review the numbers before December 31 so there is time to gather records and evaluate options.
A Simple Year-End Tax Planning Checklist
- Review year-to-date income
- Review major expenses
- Identify potential deductions
- Review planned equipment purchases
- Check retirement contribution options
- Review estimated tax payments
- Reconcile financial records
- Organize receipts and supporting documents
- Review contractor and payroll records
- Speak with a qualified tax professional about situation-specific decisions
How TaxProNext Can Help With Small Business Tax Planning
TaxProNext supports small businesses with taxation, accounting and bookkeeping, business setup, business consulting, payroll services, and virtual assistance. For year-end planning, these services can support financial records, tax and accounting information, payroll responsibilities, and broader business needs.
Its taxation services include tax planning and preparation, and tax compliance. Accounting and bookkeeping services include transaction maintenance, bank reconciliation, financial reporting, budgeting, and forecasting. Business setup, consulting, and payroll services address related operational and administrative needs.
Relevant TaxProNext services: Taxation | Business Setup | Accounting & Bookkeeping | Business Consultants | Payroll Services
Services needed depend on structure and circumstances; situation-specific decisions should be reviewed against current IRS rules.
Conclusion
Year-end tax planning is mainly about reviewing the numbers early, identifying legitimate opportunities, organizing records, and making informed decisions before the tax year closes. Reviewing deductions, equipment plans, retirement contributions, estimated payments, and accounting records can give a small business a clearer picture of what needs attention.
Tax rules vary by structure, accounting method, income, and circumstances. A qualified tax professional can help determine which options apply and how to document them.
TaxProNext provides taxation, accounting and bookkeeping, business setup, business consulting, payroll, and virtual assistance.
FAQs
What should small businesses do before year-end for taxes?
Small businesses should review year-to-date income and expenses, potential deductions, equipment purchases, retirement contributions, estimated tax payments, payroll records, and supporting documents. The goal is to identify legitimate planning opportunities and correct recordkeeping gaps before the tax year closes.
How can a small business reduce taxes before year-end?
A business can review qualifying deductions, planned equipment purchases, retirement contributions, available credits, and income or expense timing where permitted. The appropriate approach depends on the business's structure, accounting method, income, and eligibility. Tax planning should not involve unnecessary spending simply to obtain a deduction.
What tax deductions should a small business consider before year-end?
Businesses can review ordinary and necessary operating expenses such as qualifying supplies, software, professional services, insurance, and other business costs. Whether an expense is deductible depends on the facts and applicable rules. Businesses should keep documentation showing the business purpose, amount, and timing.
When should small businesses start year-end tax planning?
Small businesses should begin reviewing their tax position before year-end rather than waiting until tax-return preparation. Starting earlier provides time to review financial results, evaluate planned purchases or contributions, organize records, and discuss situation-specific decisions with a qualified tax professional.
What expenses can a small business prepay for tax purposes?
Prepaid expenses are subject to timing rules, so paying an expense before year-end does not automatically make the full amount deductible in that year. Cash-basis businesses may generally deduct expenses when paid, but prepaid costs may need to be allocated over the period they cover. Accrual rules differ.
How can businesses prepare for year end taxes?
Businesses can reconcile financial accounts, organize receipts and invoices, review bank and credit-card records, check payroll and contractor documentation, identify asset purchases, and compare estimated tax payments with expected liability. Complete records make tax preparation easier and help support deductions reported on the return.